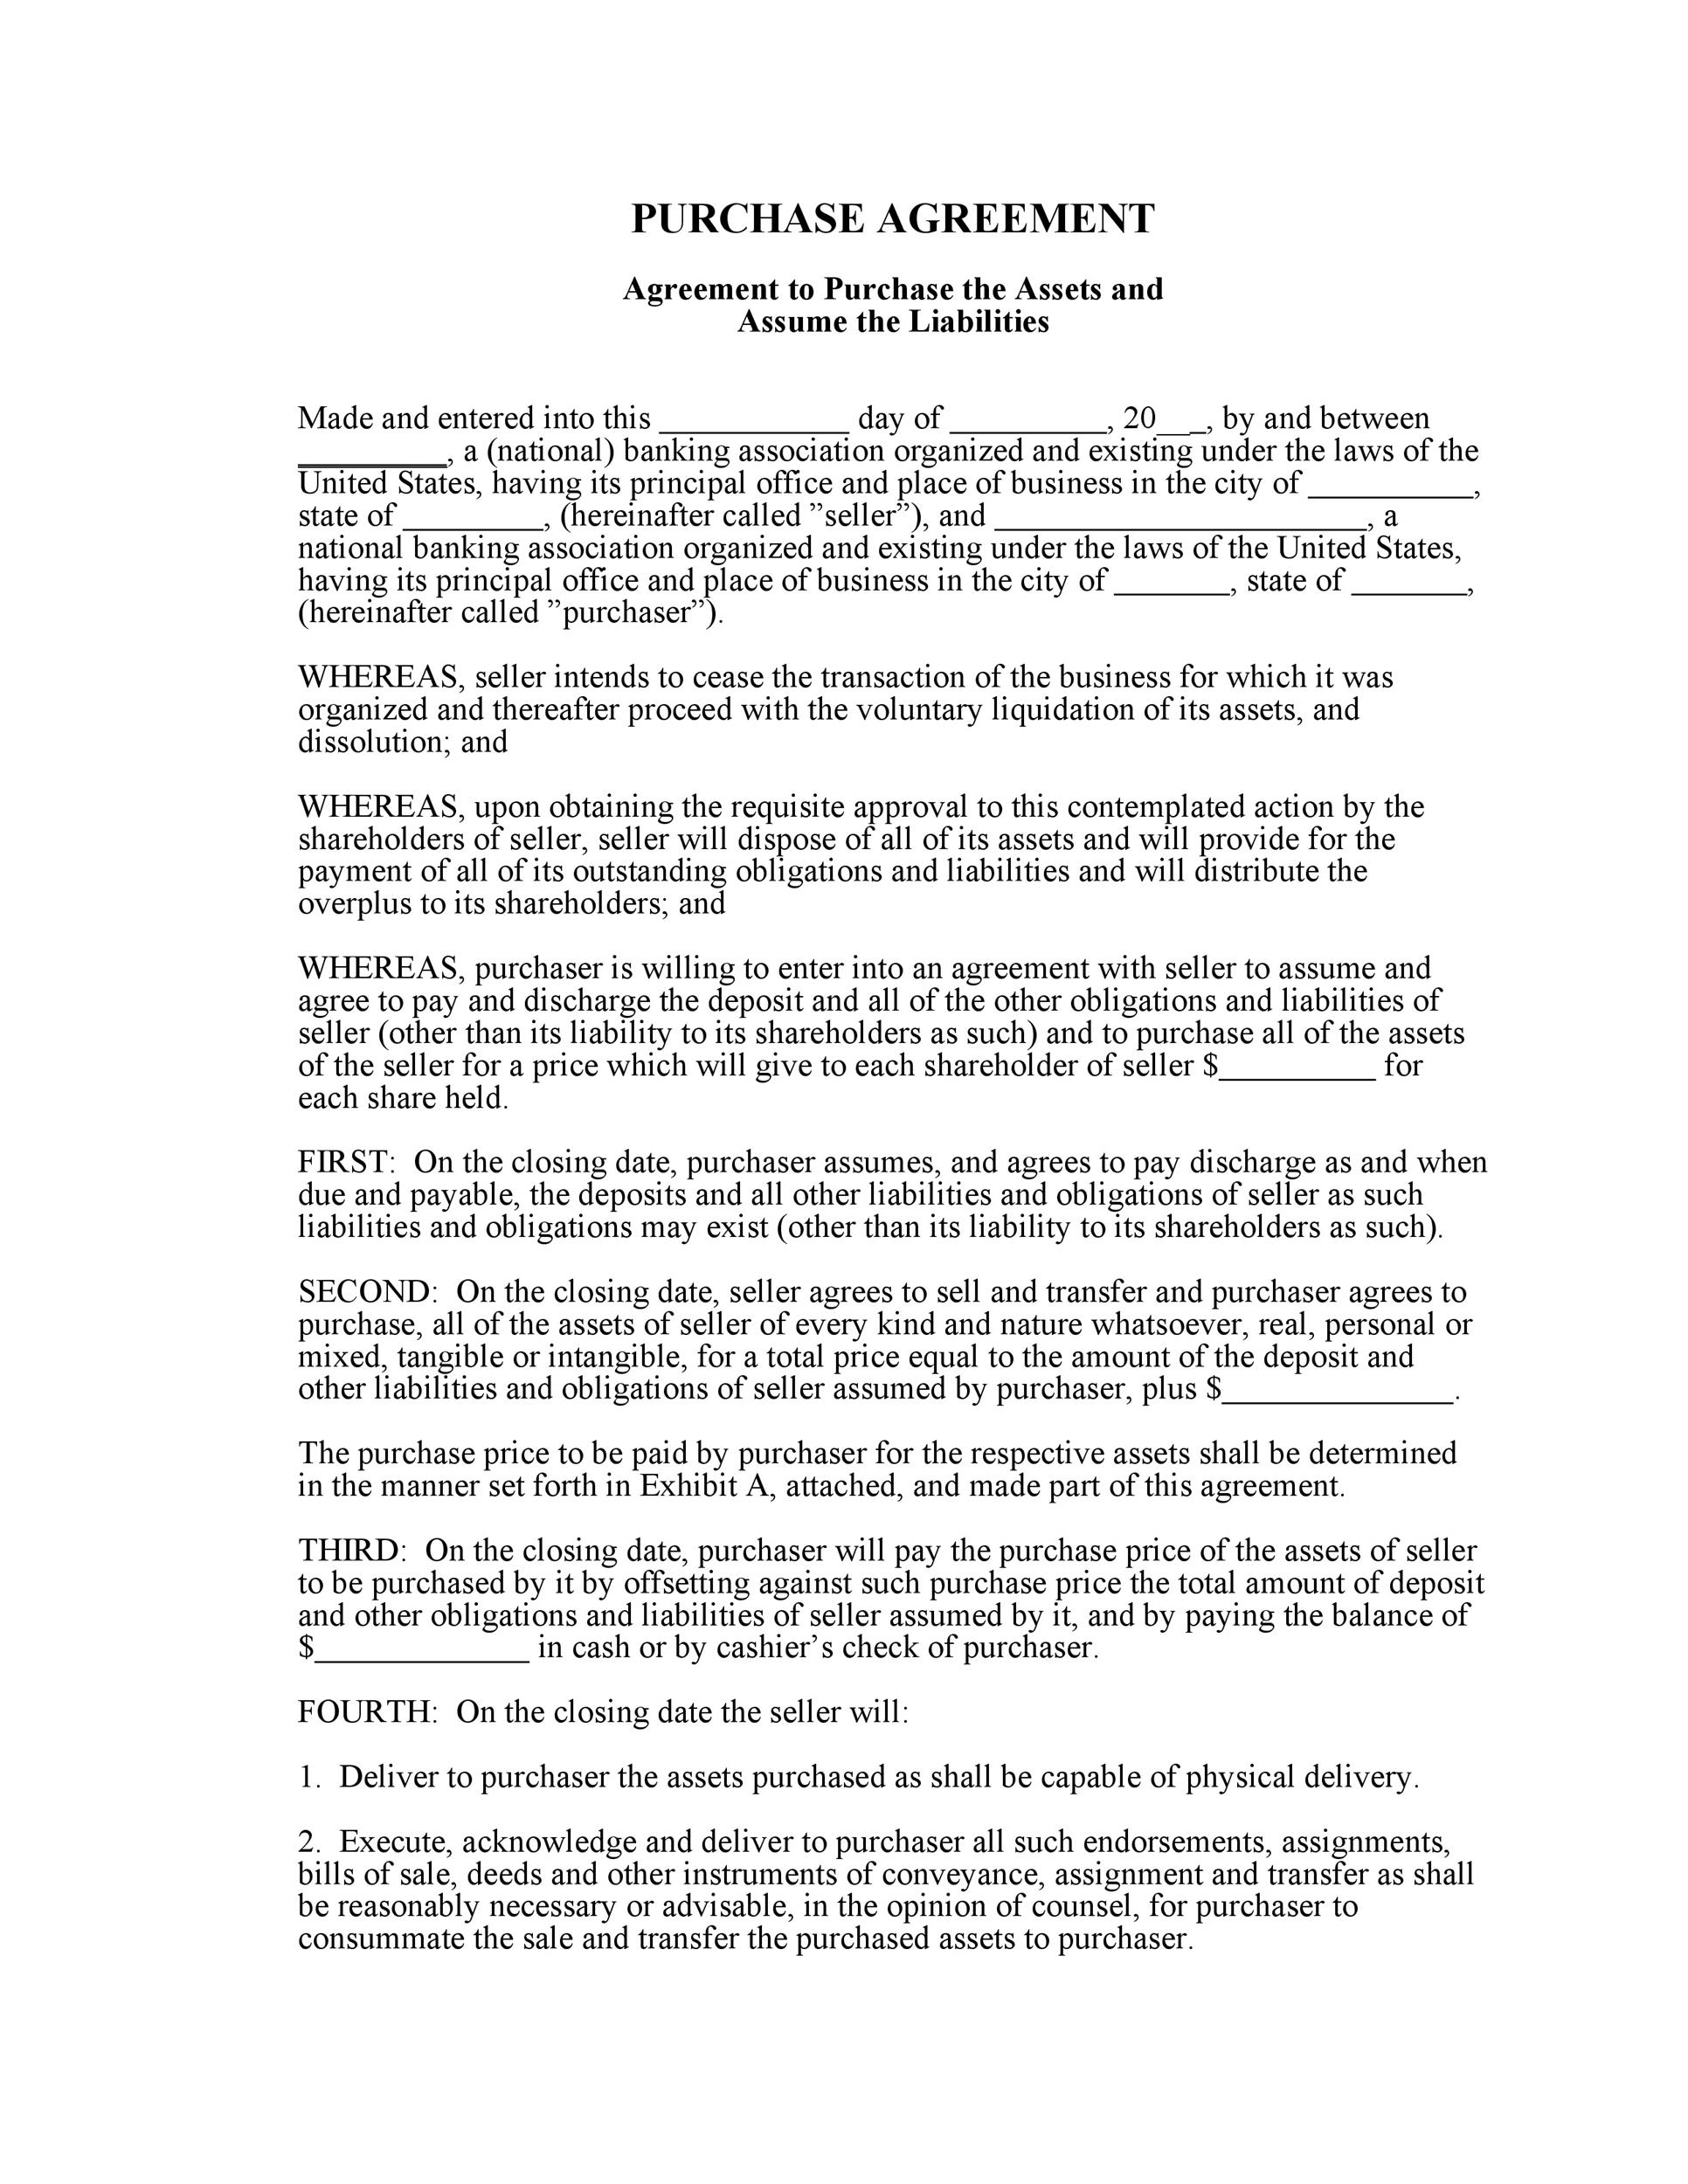
Credit Purchase Agreement Template is the dark backbone of any transaction where goods are acquired on credit, and without it, the parties risk drifting into a legal abyss where obligations blur and disputes erupt like midnight thunder.
Why a Credit Purchase Agreement Template Matters
In the murky world of credit‑based commerce, a template acts as a pre‑crafted shield against ambiguity. It forces the parties to confront the harsh realities of repayment schedules, interest calculations, and default consequences before the ink dries. By standardizing language, a template eliminates the guesswork that often fuels costly litigation, and it gives both seller and buyer a clear map of their obligations.
Beyond risk mitigation, a well‑engineered template accelerates the closing process. Rather than drafting a fresh agreement from scratch for every deal, businesses can simply plug in the specifics—price, credit limit, and delivery terms—while the core legal scaffolding remains unchanged. This not only saves time but also ensures consistency across multiple transactions, a factor that investors and auditors scrutinize with a cold, unforgiving eye.
Key Components of a Robust Credit Purchase Agreement
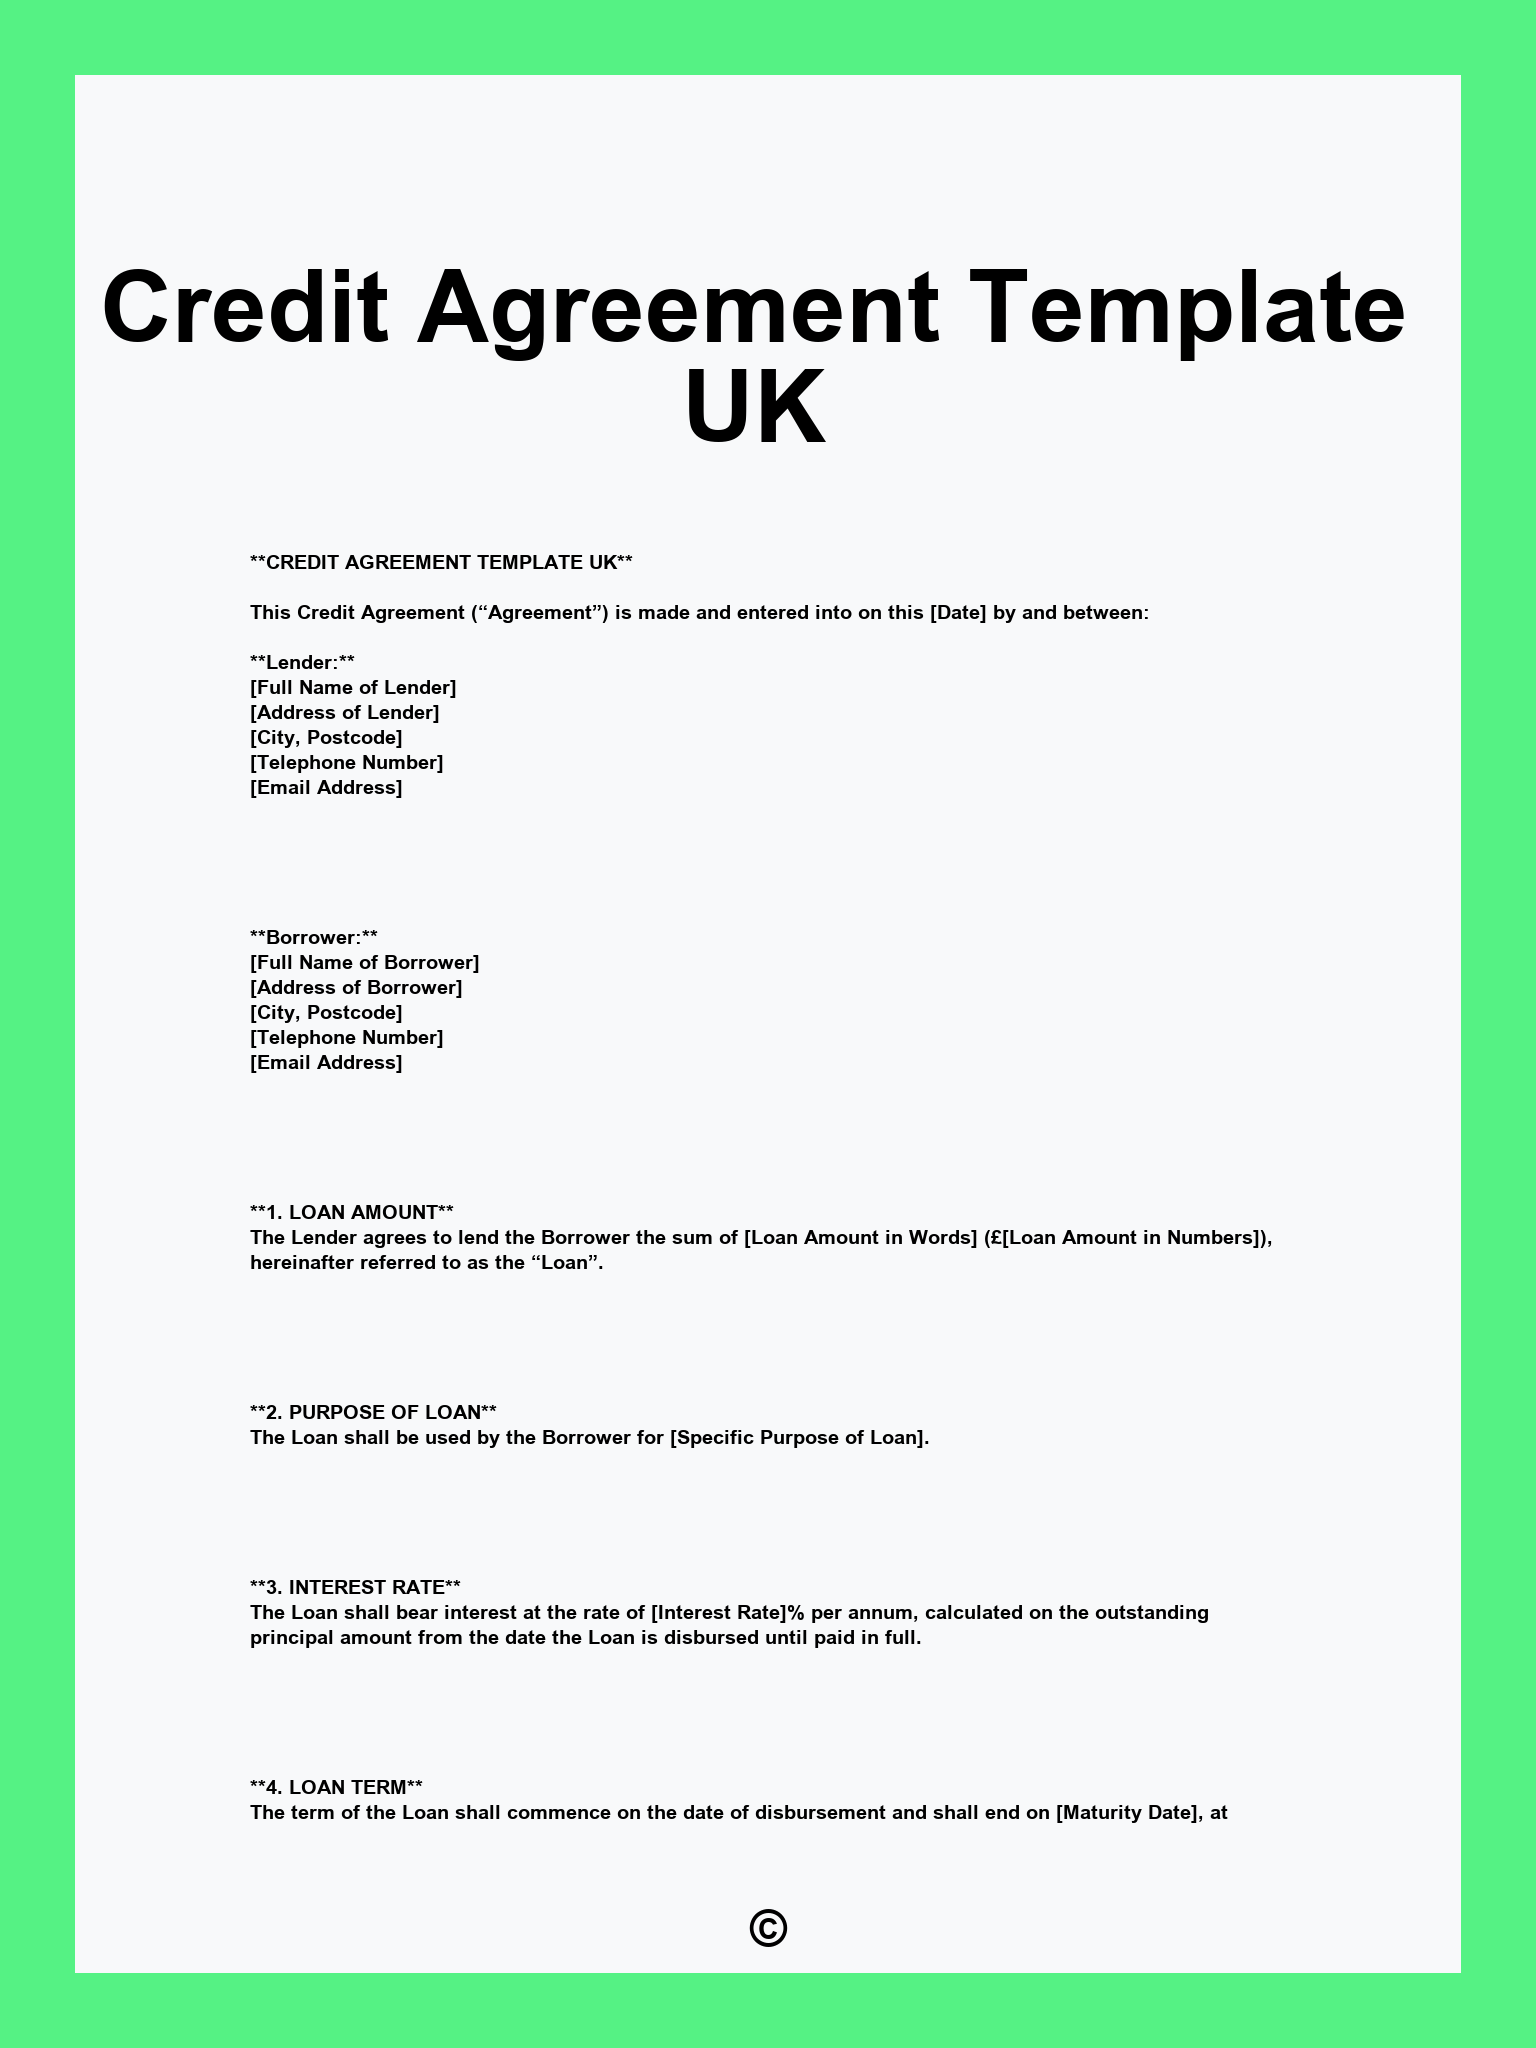
Every credible credit purchase agreement template must contain a set of non‑negotiable pillars. Miss one, and the whole structure could collapse under pressure.
Identification of Parties
Clearly define the seller and the buyer, including legal names, registered addresses, and any relevant corporate identifiers. Ambiguity here can lead to disputes over who holds the rights and responsibilities, especially when subsidiaries or parent companies are involved.
Credit Limit and Purchase Price
Specify the maximum amount of credit extended and the method for determining the purchase price of each item or service. Include provisions for price adjustments due to market fluctuations, taxes, or additional fees, because hidden costs are the most insidious traps.
Repayment Terms
Detail the schedule, frequency, and method of payment. Include interest rates, grace periods, and penalties for late payment. Use precise language such as “interest shall accrue at a fixed rate of 8.5% per annum on any overdue amount, calculated daily.”
Security and Collateral
If the seller requires security, outline the type of collateral, its valuation, and the process for enforcement. This clause often determines whether a default can be contained or spirals into a full‑scale financial crisis.
Default and Remedies
Define what constitutes a default—missed payments, insolvency, breach of covenants—and list the remedies available to the non‑defaulting party, such as acceleration of debt, seizure of collateral, or termination of the agreement. The language should leave no room for interpretation, as courts will dissect every nuance.
Governing Law and Jurisdiction
State the governing law and the exclusive jurisdiction for any disputes. In cross‑border transactions, choosing a neutral jurisdiction can prevent the parties from being dragged into unfamiliar legal systems.
Miscellaneous Provisions
Include confidentiality, assignment, amendment procedures, and force‑majeure clauses. These “catch‑all” sections may seem peripheral, but they often become the decisive factors when unforeseen events strike.
How to Customize Your Template for Different Scenarios
A generic template is a skeleton; customization adds the flesh that makes it functional for specific industries or transaction types. Below are common scenarios and the adjustments they demand.
Retail Purchases on Credit
Retail deals often involve a high volume of low‑value items. The template should incorporate a streamlined invoicing system, automated interest calculations, and a clear return policy that ties back to the credit terms.
Industrial Equipment Financing
For capital‑intensive equipment, the template must emphasize collateral valuation, maintenance obligations, and insurance requirements. A clause allowing the seller to inspect and certify equipment condition before each payment can protect against premature wear.
Software as a Service (SaaS) Subscriptions
When credit is extended for subscription services, the agreement should address usage limits, data ownership, and the consequences of non‑payment on service continuity. A “termination for cause” clause that automatically suspends access upon default is essential.
Cross‑Border Transactions
International deals bring currency risk, import duties, and differing legal frameworks. Include a currency conversion clause, specify which party bears customs fees, and choose a neutral governing law—often English law—for predictability.
Common Pitfalls and How to Avoid Them
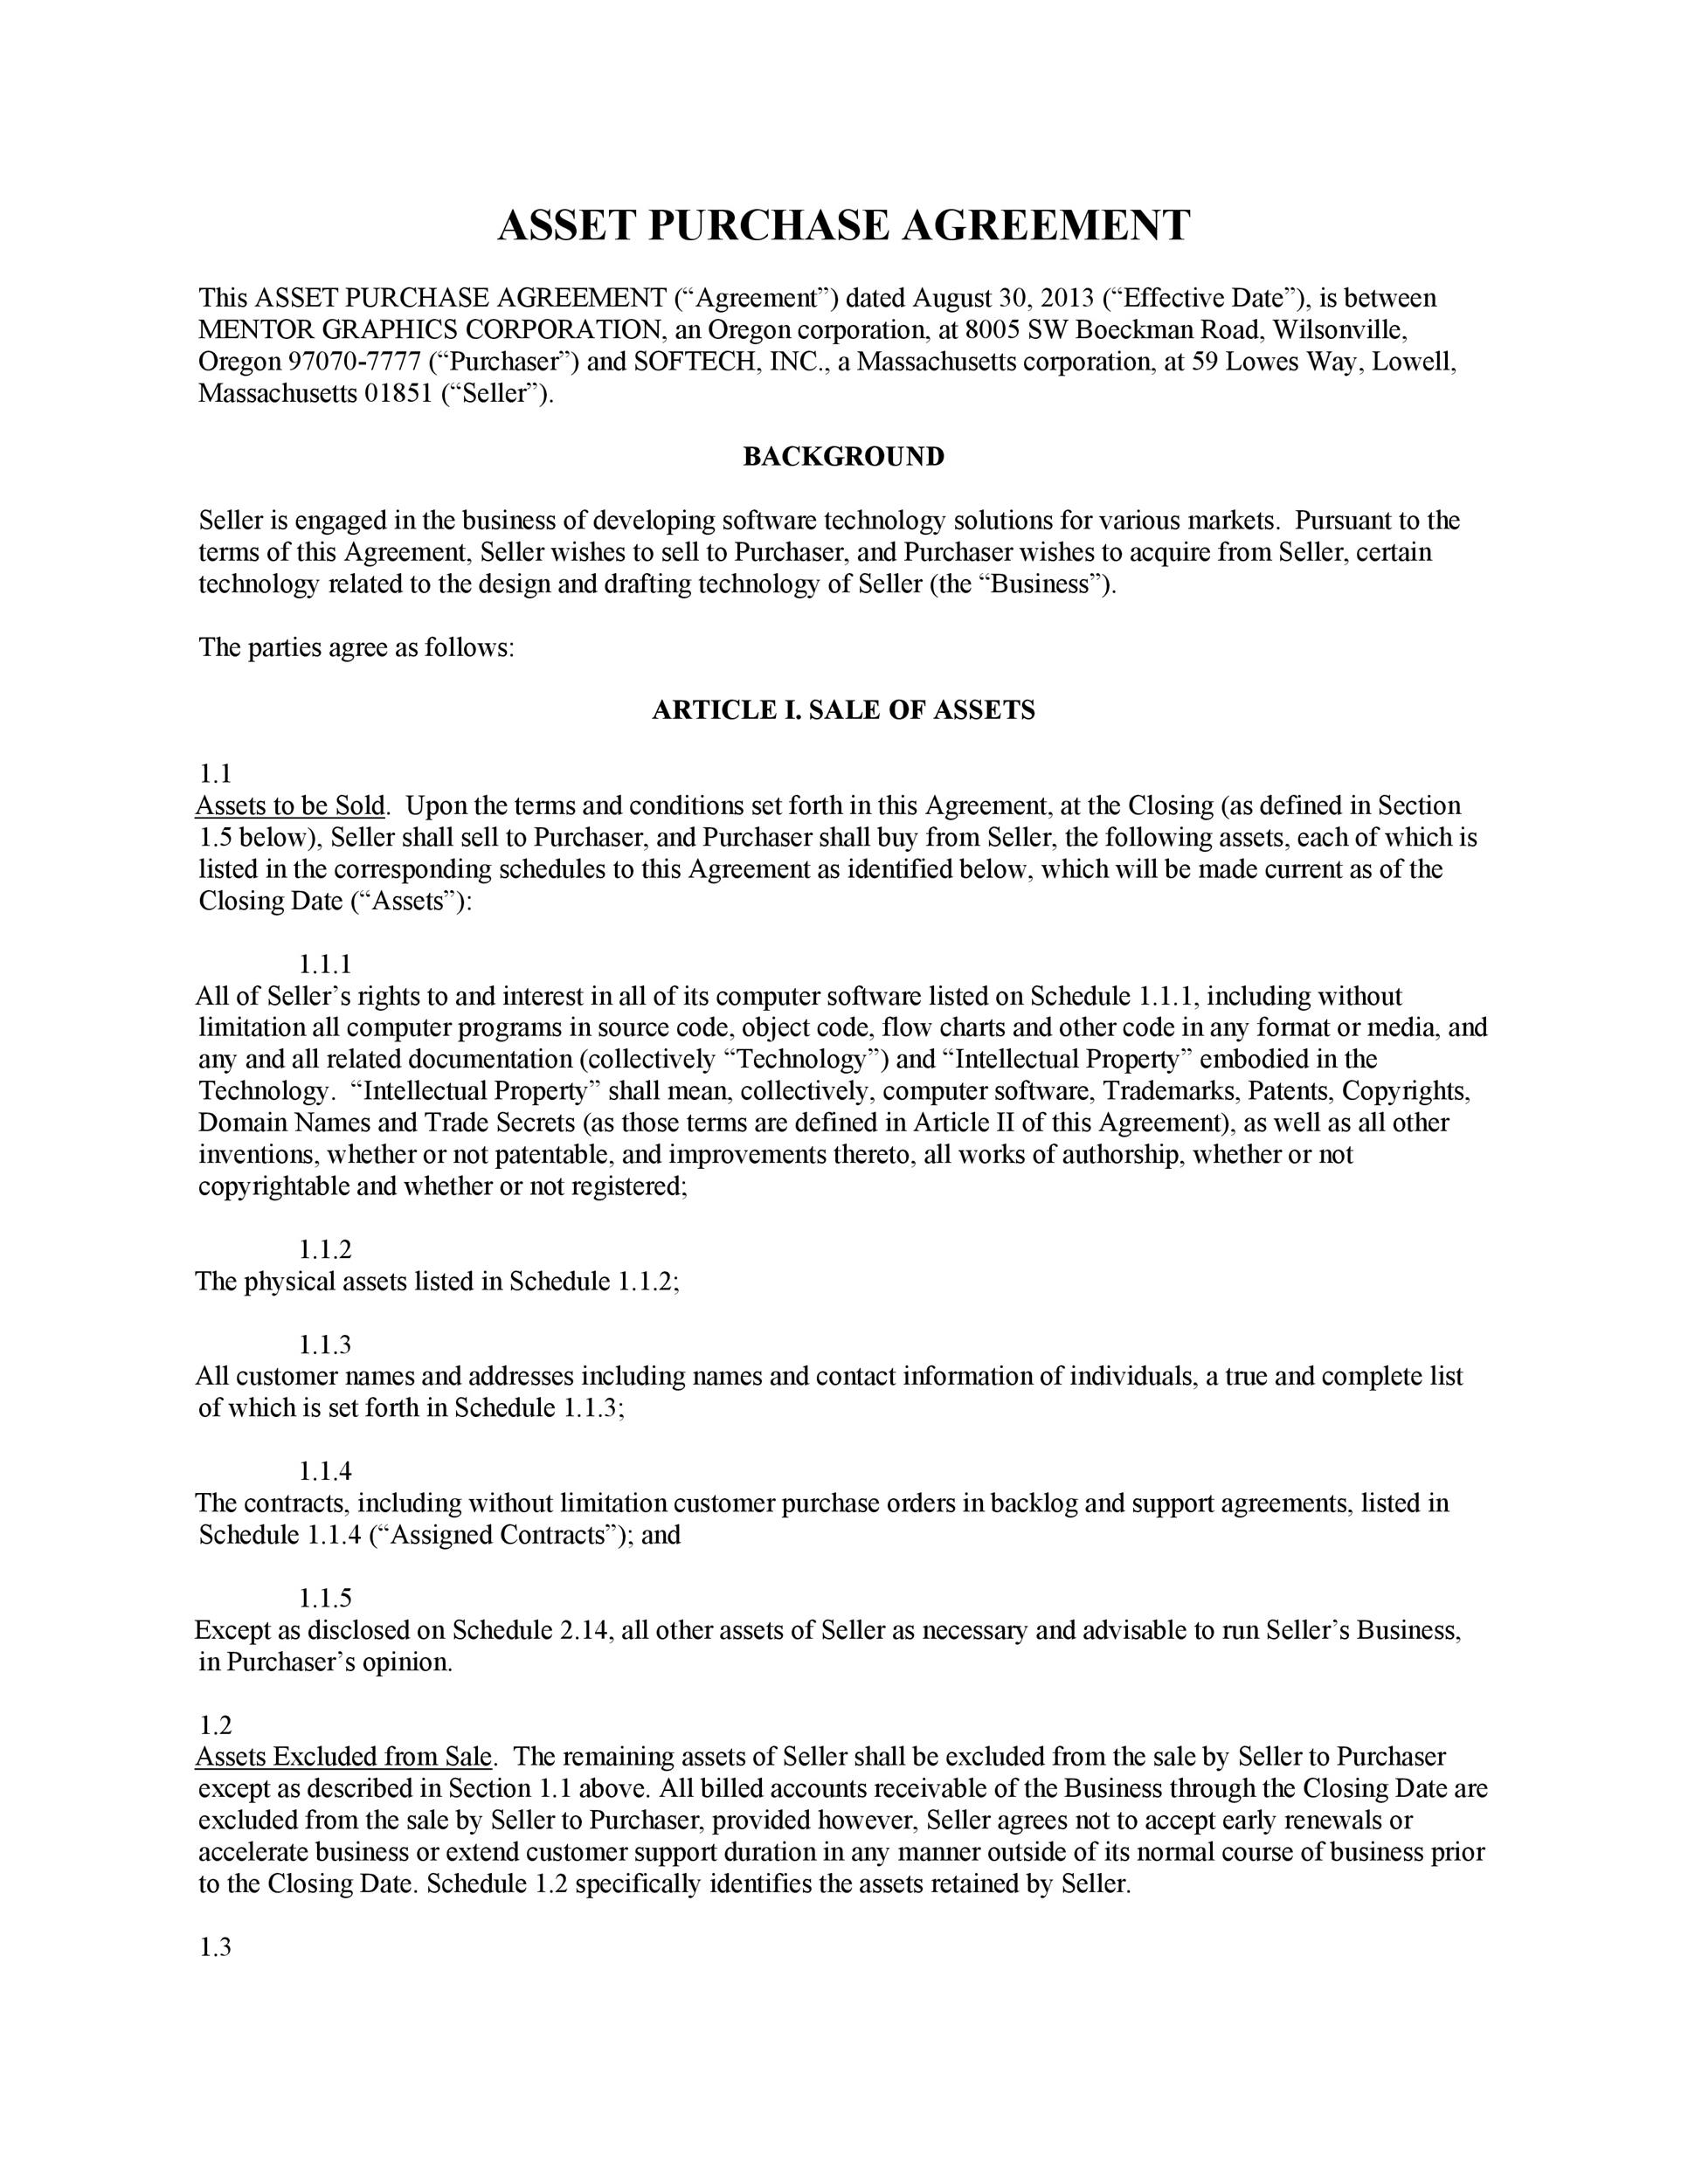
Even seasoned negotiators can stumble into traps that transform a well‑intended credit purchase agreement into a nightmare.
Vague Interest Calculations
Never rely on ambiguous language like “interest at a reasonable rate.” Instead, set a fixed rate or reference a recognized benchmark (e.g., LIBOR plus a spread). This eliminates disputes over what is “reasonable.”
Inadequate Security Provisions
Leaving collateral undefined or failing to detail the enforcement process can render the security meaningless. Always include a detailed description, valuation method, and a step‑by‑step enforcement plan.
Overlooking Tax Implications
Credit agreements often trigger sales tax, value‑added tax, or withholding tax obligations. Integrate a tax clause that clarifies which party bears each tax, and include mechanisms for tax adjustments.
Failure to Update Templates
Legal landscapes evolve. A template that once complied with regulations may become obsolete after a legislative change. Conduct a quarterly review of the template with legal counsel to keep it current.
Step‑by‑Step Guide to Drafting Your Own Agreement
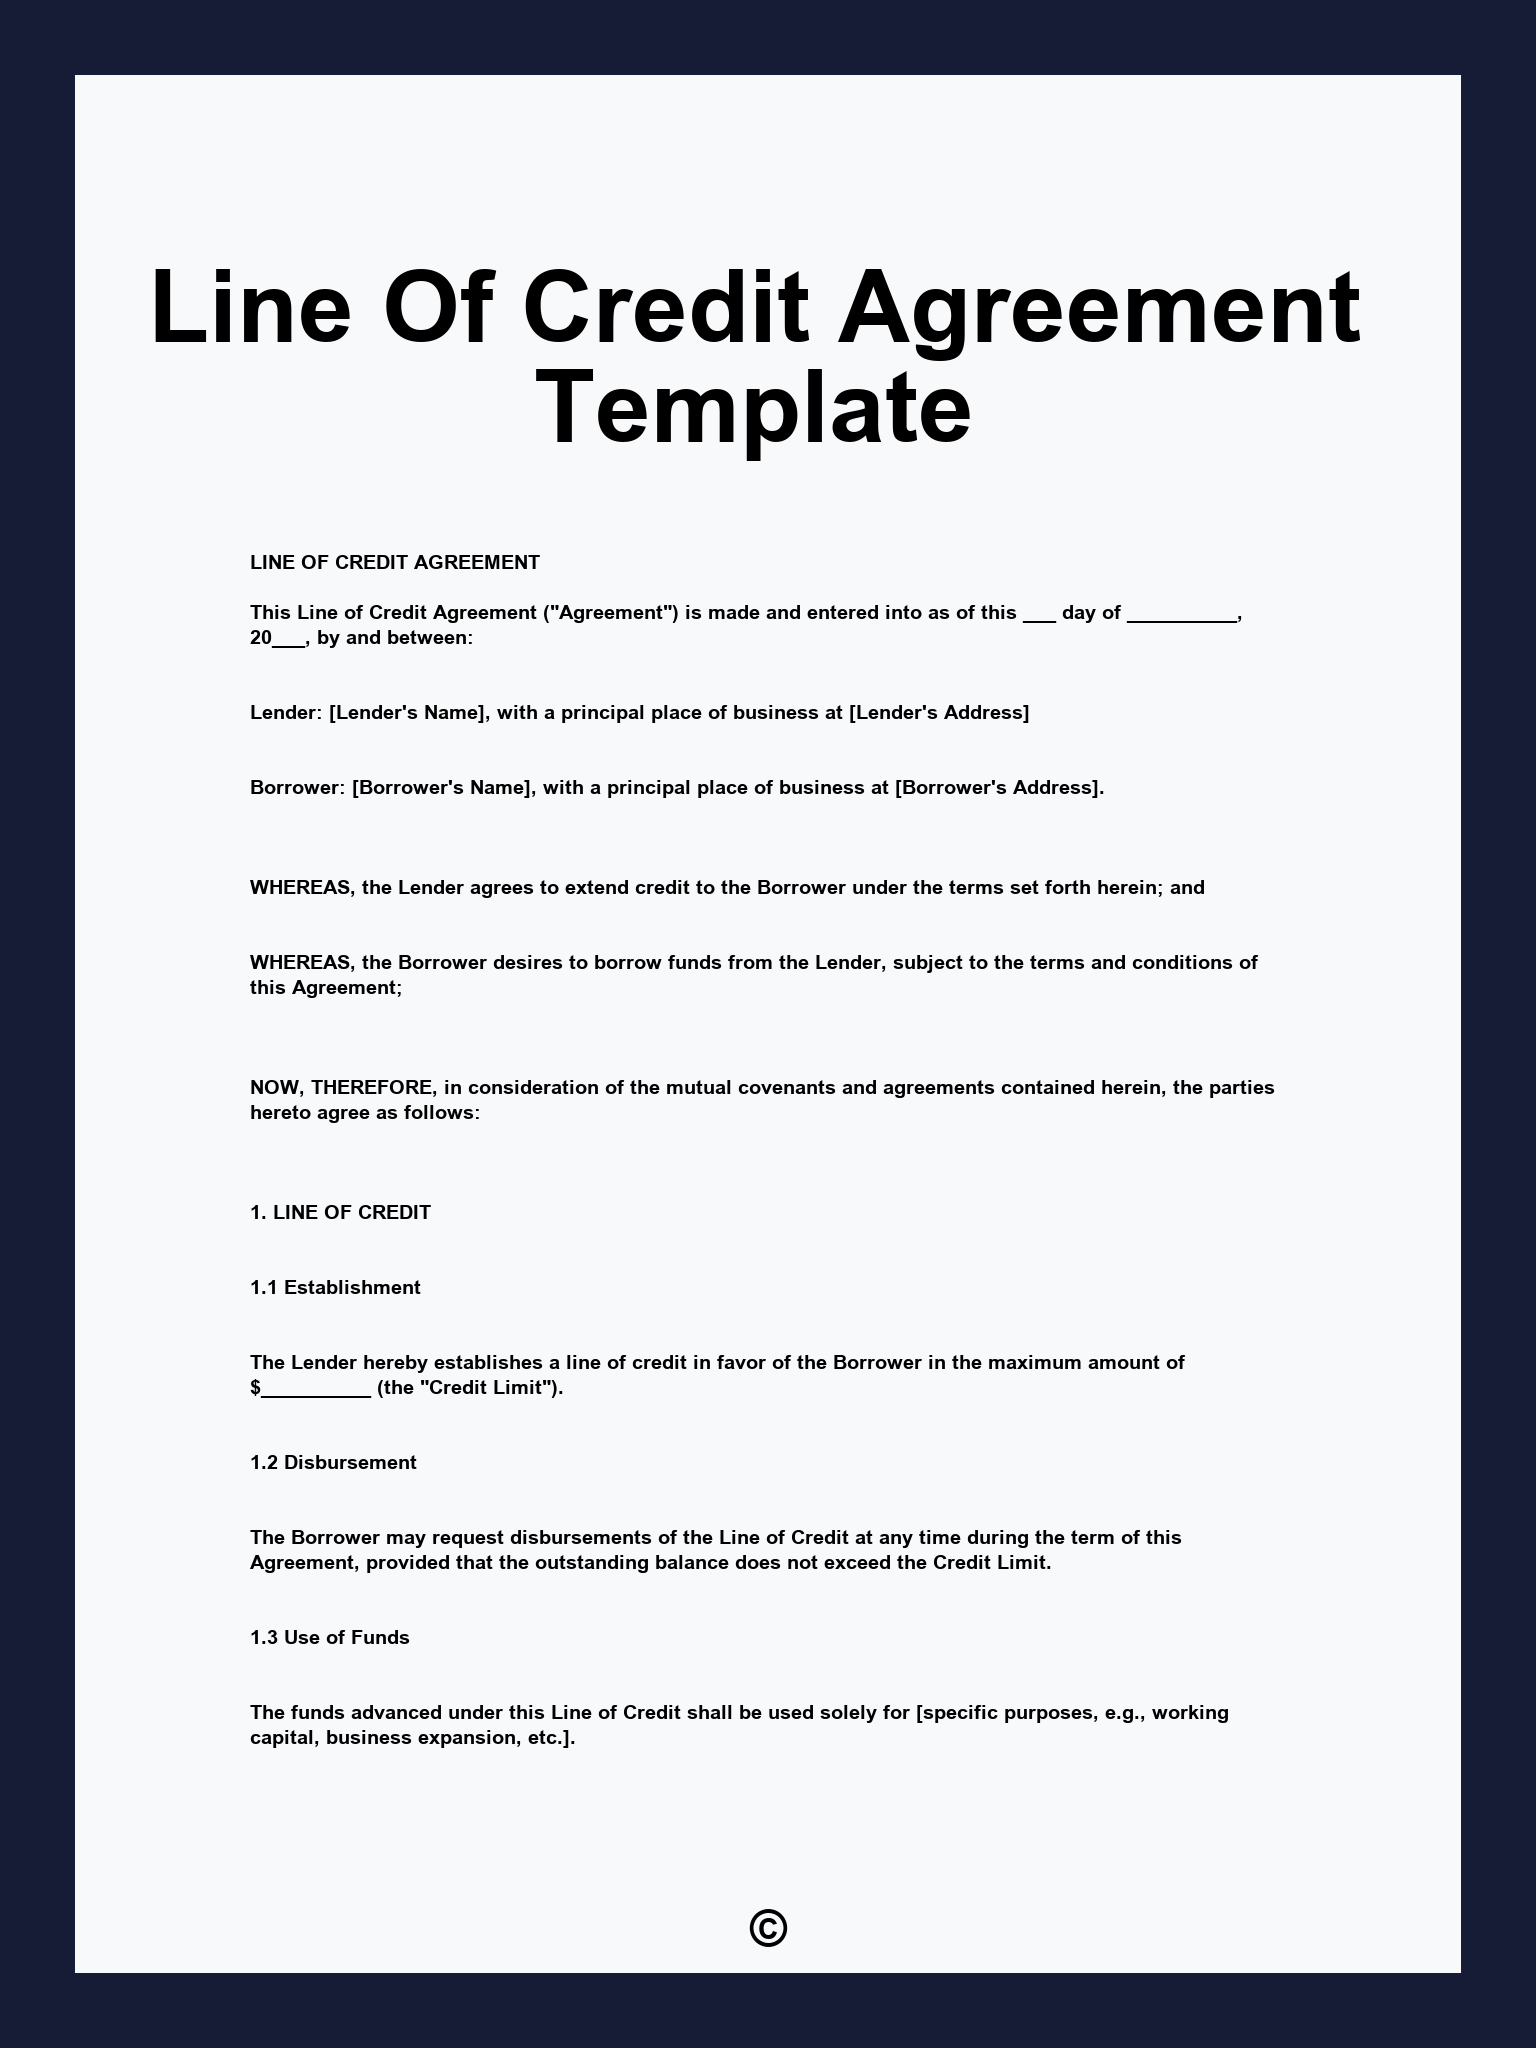
Follow this meticulous process to forge a credit purchase agreement that can withstand scrutiny and enforceability challenges.
Step 1: Gather Transaction Details
Collect all essential data: parties’ legal names, credit limit, product description, price per unit, delivery schedule, and payment cadence. Missing information at this stage creates gaps that later become liabilities.
Step 2: Choose a Base Template
Select a reputable credit purchase agreement template as the foundation. Ensure it includes the core components listed earlier, and verify that it aligns with the jurisdiction governing your transaction.
Step 3: Insert Specific Terms
Replace placeholders with actual figures and dates. For example, change “[Credit Limit]” to “$250,000” and “[Interest Rate]” to “8.5% per annum, fixed.” Double‑check that every placeholder is addressed.
Step 4: Tailor Security Clauses
If collateral is required, draft a detailed description—e.g., “one (1) 2022 Ford F‑150 pickup truck, VIN 1FTFW1EF5EKF12345, valued at $35,000.” Attach an appraisal report as an exhibit.
Step 5: Integrate Compliance Checks
Run the draft through a compliance checklist: does it comply with usury laws? Are there any prohibited terms under the Uniform Commercial Code (UCC) or the Federal Trade Commission regulations? Resolve any red flags before proceeding.
Step 6: Review and Negotiate
Circulate the draft to the counterparty’s counsel. Expect revisions—especially on interest, penalties, and jurisdiction. Keep the tone firm but professional; a black‑tone approach does not mean being hostile, merely unflinching.
Step 7: Execute with Formalities
Both parties must sign the agreement in the presence of a notary if required by local law. Retain original copies and store digital versions in a secure, encrypted repository.
Step 8: Implement Monitoring Systems
Set up an automated reminder system for due dates, interest accrual, and collateral inspections. Early detection of payment delays can trigger remedial actions before the situation escalates.
Legal Considerations and Compliance
Credit purchase agreements operate at the intersection of contract law, secured transactions, and consumer protection statutes. Ignoring any of these domains invites litigation and regulatory penalties.
Usury and Interest Rate Limits
Each state imposes a maximum allowable interest rate. Exceeding this cap transforms interest charges into unlawful penalties, rendering the entire agreement unenforceable. Verify the applicable rate before finalizing the clause.
Uniform Commercial Code (UCC) Article 9
If the agreement creates a security interest in personal property, Article 9 governs perfection, priority, and enforcement. Ensure that a financing statement is filed with the appropriate state office within the statutory deadline.
Consumer Protection Laws
When dealing with individuals rather than businesses, the agreement must comply with the Truth in Lending Act (TILA) and the Fair Debt Collection Practices Act (FDCPA). Disclose all costs up front and avoid deceptive practices.
Anti‑Money Laundering (AML) Regulations
Large credit extensions can trigger AML reporting obligations. Include a clause obligating the buyer to provide beneficial ownership information and to cooperate with any AML investigations.
Best Practices for Execution and Management
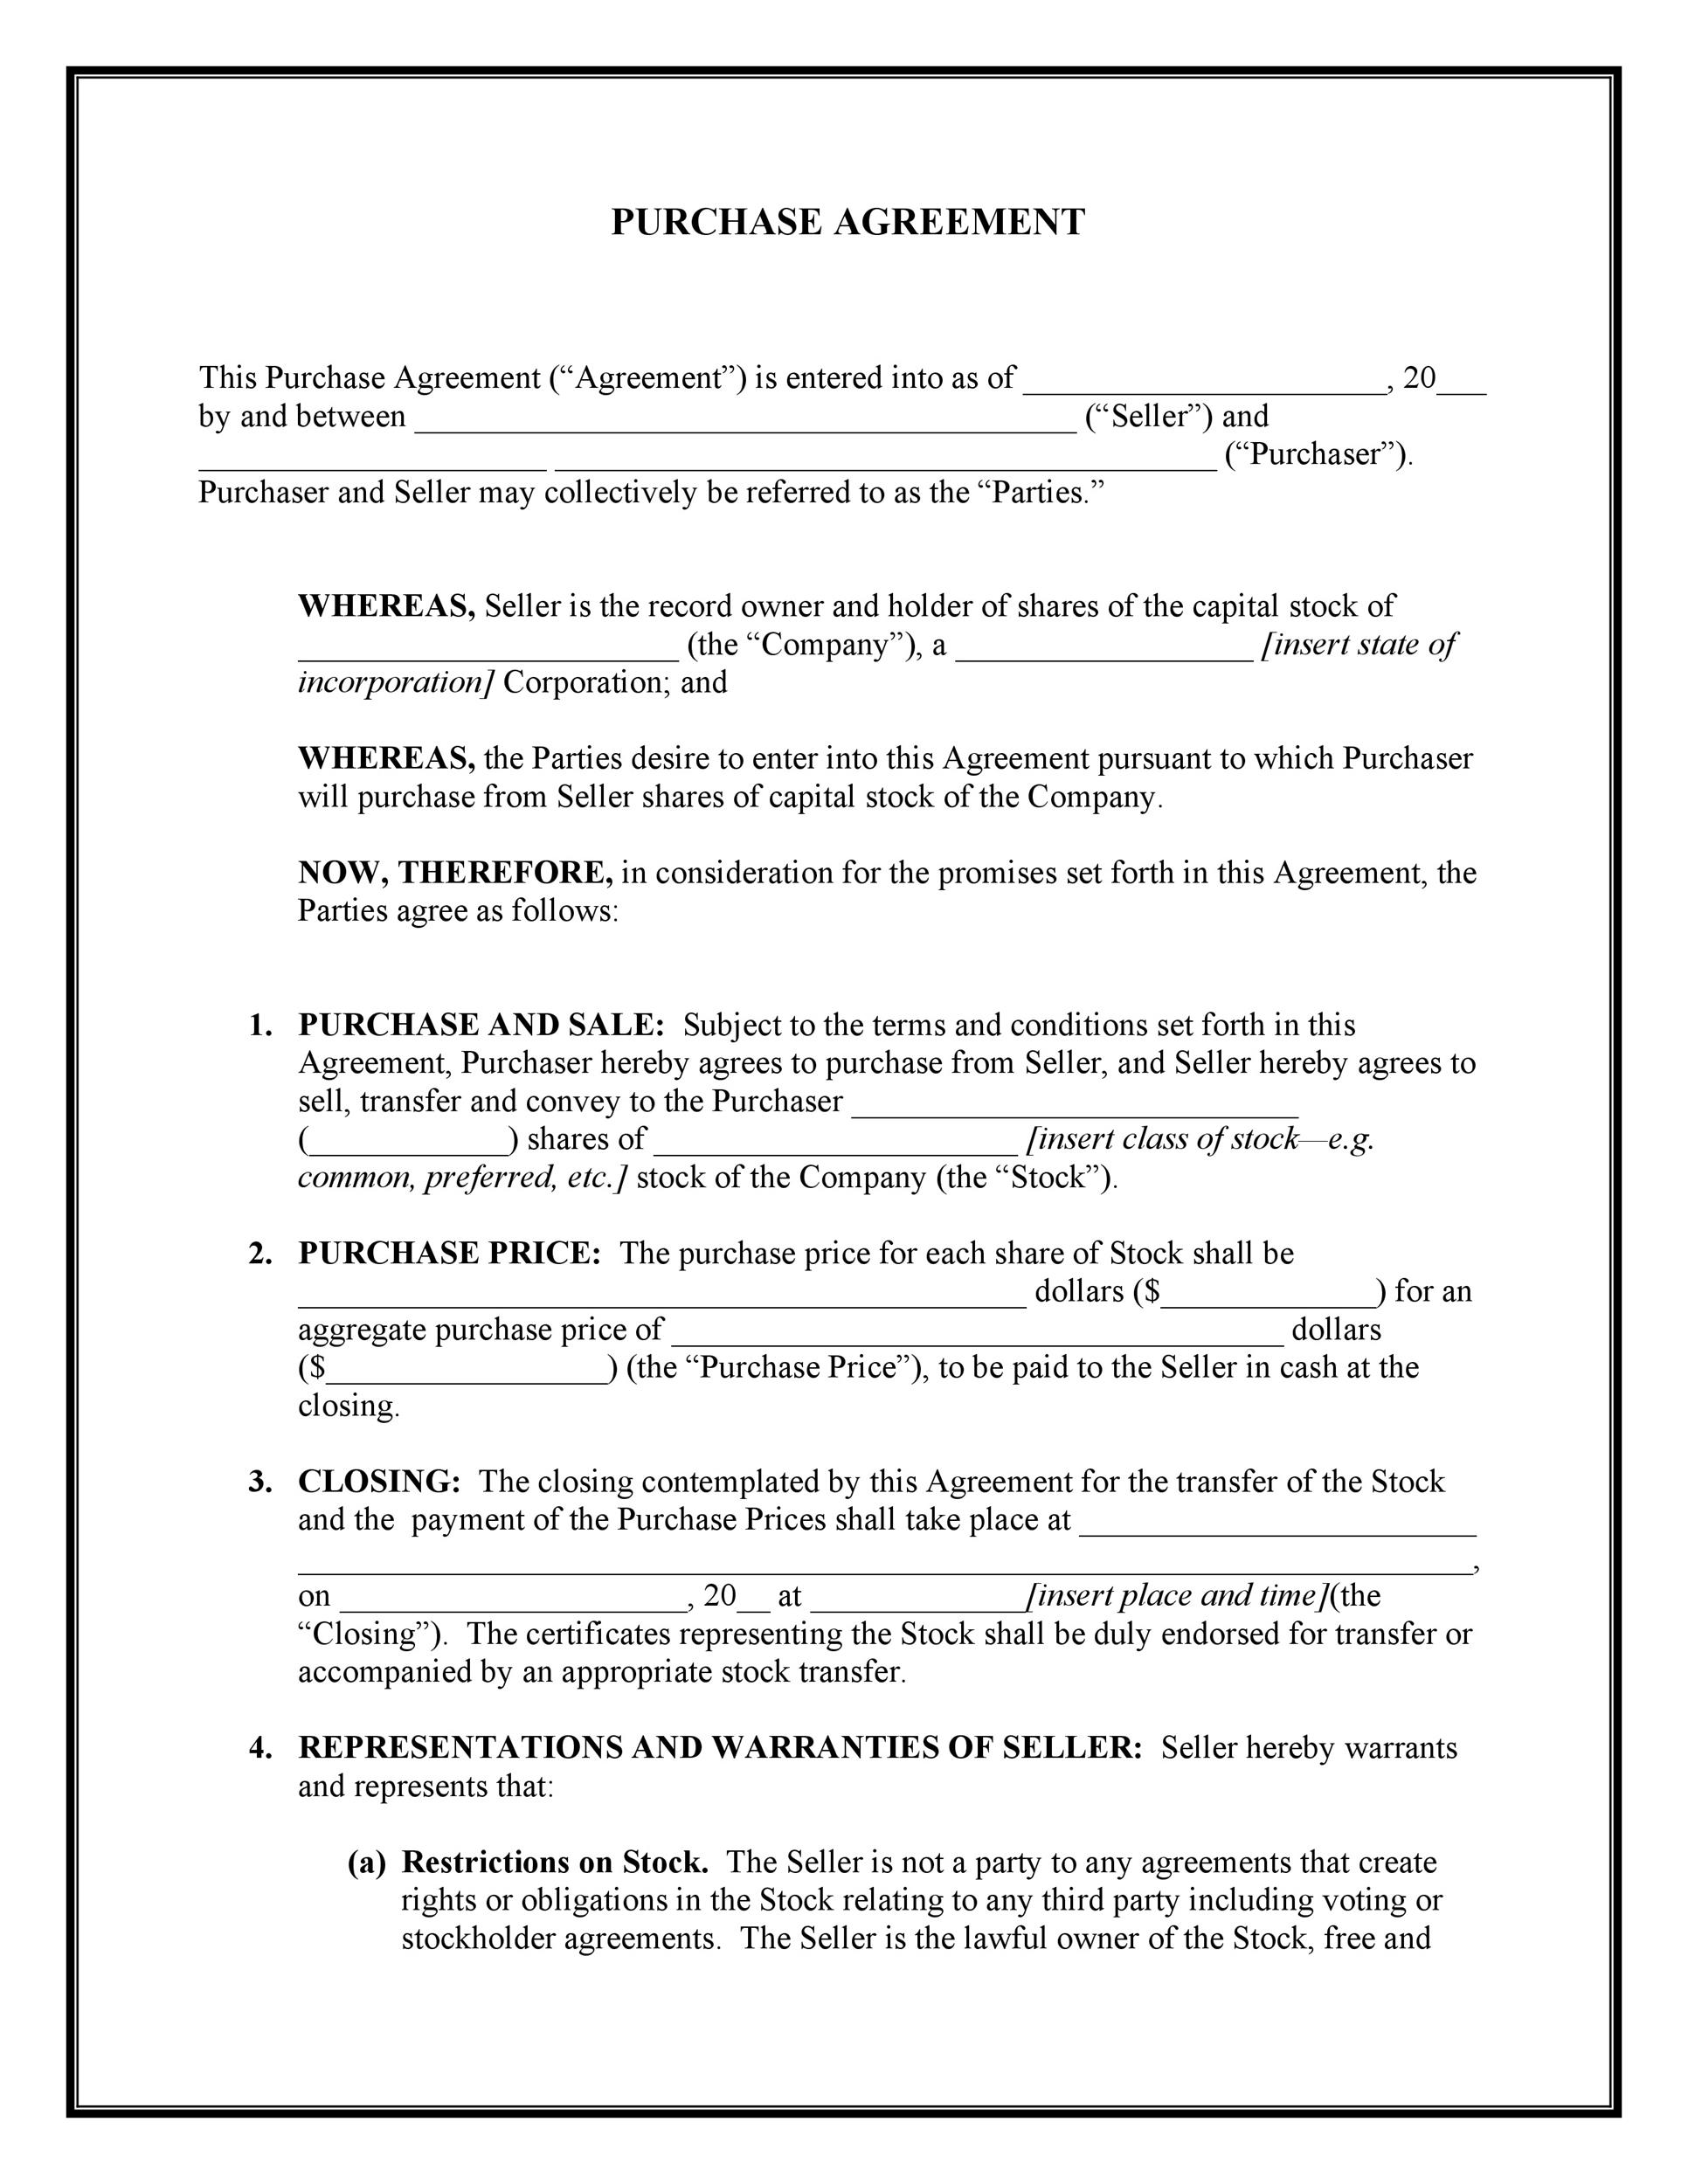
Drafting the agreement is only half the battle; managing it over its life cycle determines whether the credit relationship thrives or withers.
Maintain an Audit Trail
Record every amendment, payment, and communication in a centralized ledger. In the event of a dispute, a well‑documented trail can be the decisive evidence.
Regular Collateral Revaluation
Market values shift. Schedule periodic reassessments of collateral to ensure that the security remains adequate relative to the outstanding debt.
Proactive Communication
Establish a dedicated account manager to liaise with the buyer. Early, transparent dialogue about potential payment issues can prevent defaults turning into legal battles.
Utilize Automated Enforcement Triggers
Integrate contractual triggers—such as automatic acceleration of debt upon a missed payment—into your accounting software. This reduces the lag between default detection and enforcement.
Conclusion
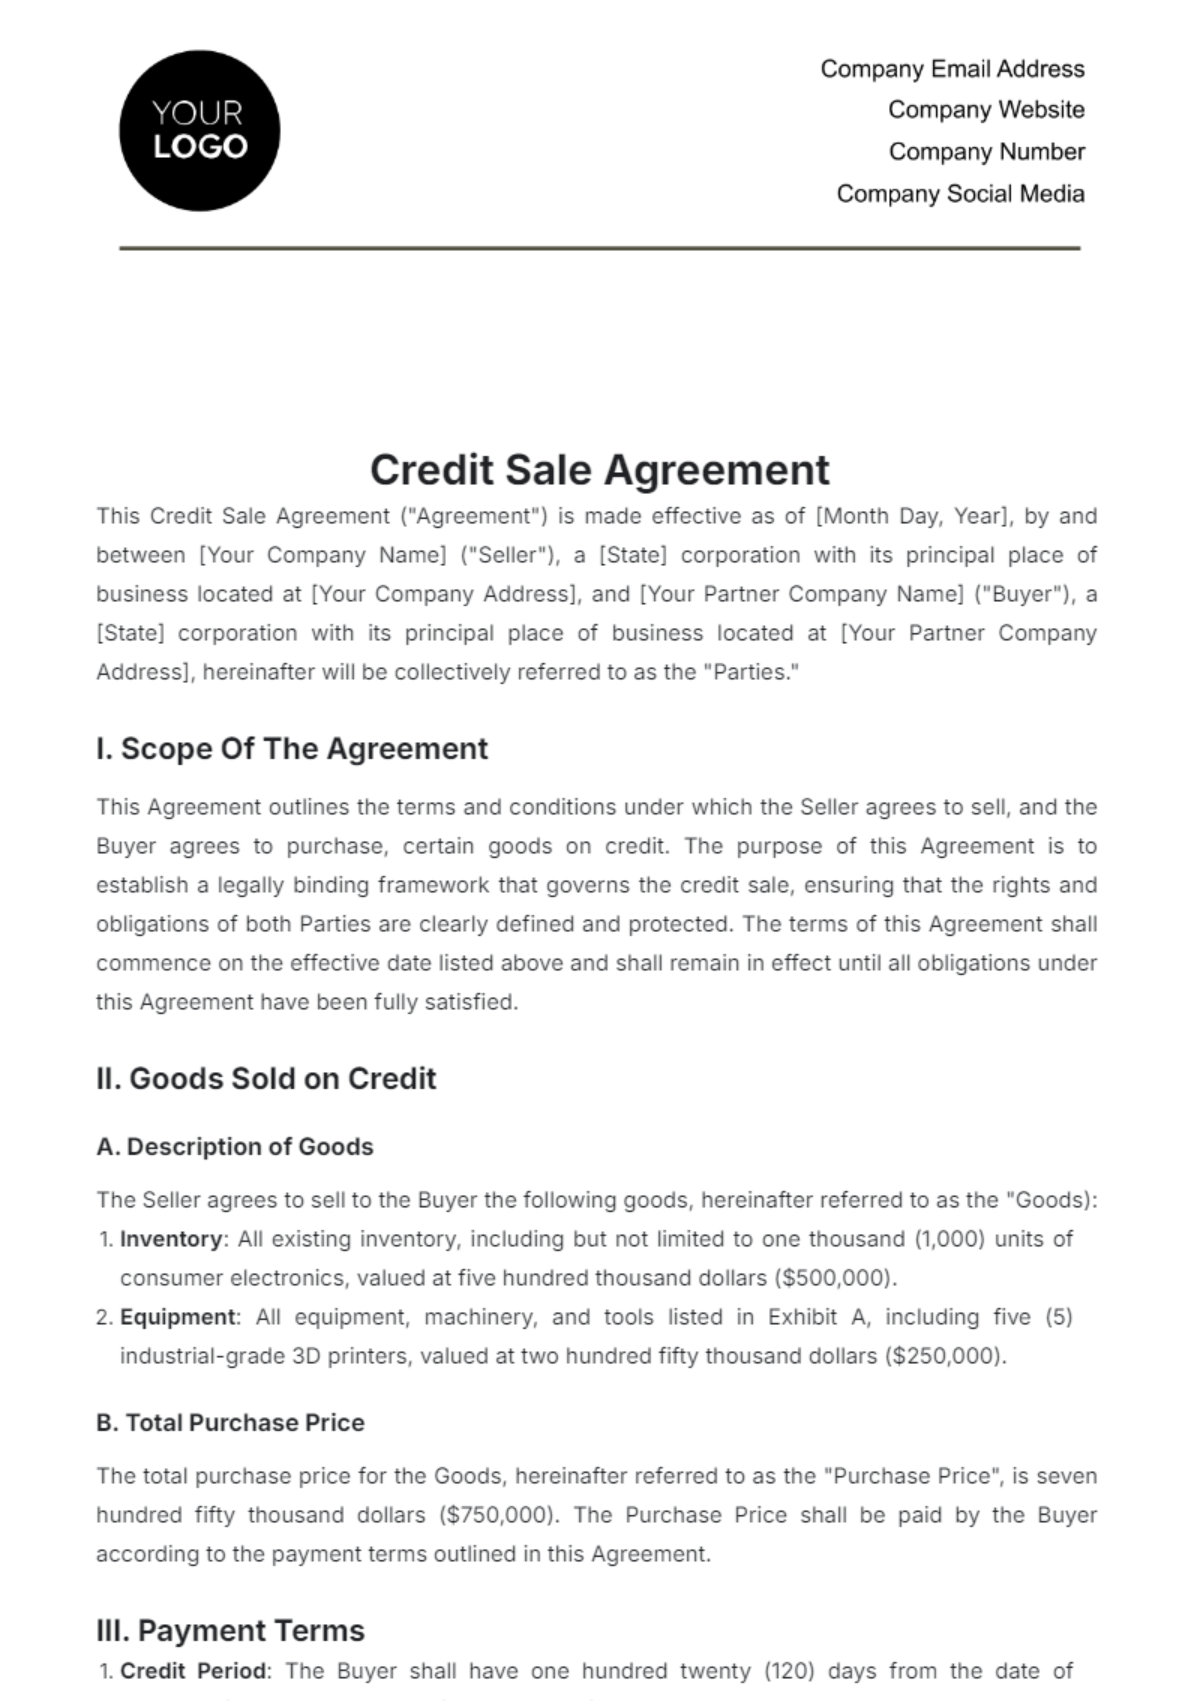
A meticulously crafted Credit Purchase Agreement Template is the ironclad contract that transforms a precarious credit transaction into a controlled, enforceable arrangement. By embedding the essential components, customizing for specific industries, and rigorously adhering to legal compliance, businesses shield themselves from the relentless darkness of financial risk. Implementing disciplined execution and vigilant management ensures that the agreement remains a living instrument—responsive to market shifts and resilient against defaults. In a world where credit can be both a lifeline and a liability, the right template is not just a document; it is the strategic weapon that secures prosperity and averts ruin.
[ssba-buttons]